Author: HairWeavings Editorial Team

Resolution, Revolution and Resistance, Taken from Dylan Thomas and Approved by Me

resolution, revolution and resistance

I tossed my walker over the cliff the other day (figuratively); I was raising my angry fist at my advancing years and infirmities, much like Dylan Thomas wrote in his famous poem.

“Do Not Go Gentle into that Good Night” (line 1)

Acceptance of this has been a battle as I deal with body part replacements, body parts deteriorating and having to be rebuilt with other body parts, and a host of other ailments.

My couch has become my new best friend. And as I watch my bird feeder outside my window, I meditate on accepting this, because, in my days under the sun, I have hiked high elevation mountains, swam with sharks and repelled down cliffs.

“Curse, Bless, Me Now with Your Fierce Tears” (line 17)

The aging of my body and mind is a given, but does it mean I have to be resigned to it? Aging is inevitable and a privilege, but to remain complicit in the face of aging is starting to wear on me. While there may be times to be on the couch and take care of my body, there also comes a time that I need to push through it.

So, I got up off the couch the other day despite painful throbbing neuralgia and arthritis. In a cool rain, with a bottle of water and fierce determination, I started hiking, uphill, climbing up boulders until I was as high as the buzzards. I felt good; illness was suddenly not in the driver seat of my life. It had moved to the backseat.

“Old Age Should Burn and Rave at Close of Day” (line 2)

A friend was convinced her COPD was getting worse – possibly her heart too. After the death of her dog, she had stopped walking, volunteering, going to the gym, and gardening made her tired. Entire weekends were spent dozing.

“You’re depressed.” I told her.

She made a face. “Nonsense; I’m 74 and have COPD. The doctors have me on a heart monitor for a month!”

The eventual diagnosis? She was just fine and out of shape. The doctors told her to start moving. My sister, 78 and spending the last two years in chemotherapy, goes shopping many days a week, has a weekly hair, nail and facial appointment, and refuses to give up and be sick.

“I simply won’t think about it,” is her motto. A colleague, Dr. P, suffering from dementia, has stepped down as VP at a college, but he is at the college frequently, tutoring students or taking classes, each semester learning something new, and he does it with unflinching grace and joy.

“Blind Eyes Could Blaze Like Meteors and Be Gay” (line 14)

I no longer have the appetite to hike to Everest Base camp (which was on my bucket list along with Mt. Kilimanjaro), or go on vacations that I used to need to train for with weighted belts, but on the days that I am well, and even on the days I’m not feeling all too well, I’m going to push forward because, for me, it feels cowardly to do otherwise.

Instead of tears coming to my eyes because the arthritis in my hands makes it hard to nimbly maneuver my fingers, I now get ticked off. A little bit of rage goes a long way, and it prevents me from wallowing in the despair of my body betraying me.

I have more years behind me instead of ahead of me. WOW. How do I live my life knowing this? How do I live my life when a new ailment seems to materialize every week? How do I live my life when my heart wants to do a triathlon, but my bilateral hip replacements won’t let me?

Get Back on the Horse?

Throwing my leg over my 23-year-old Thoroughbred the other day, I decided both he and I were not through quite yet. He agreed. Grabbing his mane, he leapt into a gallop, and we went flying like he was 8 years old and I was 27. Sparks literally flew off his horse shoes as they crossed over the rocks. We jumped a creek, a log, branches smacked me in the face, and we both felt more alive than we had in years. It was exhilarating.

Afterwards, walking like John Wayne into my house, I took an anti-inflammatory, ran a warm bath with Epsom salts; not something I needed to do when I was 27. By 9 p.m. my crunched disks in my neck were screaming, so I took more meds and added my neck brace. I had ice or hot packs on different areas of my body. But that’s o.k., I think.

Perhaps it does not need to be all or nothing. Maybe there is a middle range, somewhere that isn’t on the couch but not hiking the Appalachian Trail – though an 83-year-old has completed it. While I don’t need to gallop every day, I do need to stay engaged, moving my body, working my mind, meeting people because it’s way too easy for me to let my aging pained body be in the driver seat.

Dylan Thomas wrote, “old age should burn and rave at close of day.” Yet, he only lived till 39. Hmmmmm. But there is some truth in his poem because the theme is about not being complacent, having regrets or resignation to the aging process, which often isn’t pretty. Sometimes, to march through aging, we need to be a bit fierce.

Let’s Have a Conversation:

How are you handling the aging process with grace? Have you had to modify pastimes you have enjoyed? Can you strike a balance of rest and engagement?

Read More

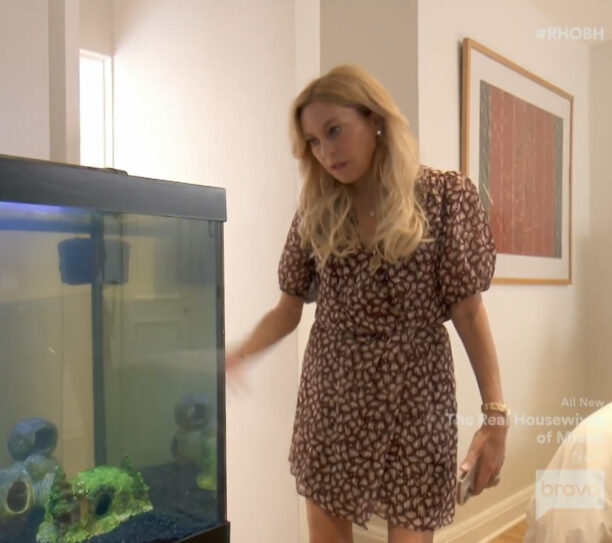
Sutton Stracke’s Burgundy Printed Dress

Sutton Stracke’s Burgundy Printed Dress / Real Housewives of Beverly Hills Season 13 Episode 10 Fashion

Sutton Stracke’s fashion and dating games have both been reaching new heights. And on last night’s episode of Real Housewives of Beverly Hills she not only had a good conversation with her “fish” but she got a phone number after a first date!

Sutton’s fashion has always been on point even if her dating skills might need some brushing up. So if you want some new looks to level up your game whether that be for a date or simply talking to your pets then keep scrolling for some inspiration. Because when it comes to style Sutton always helps us find our match.

Best in Blonde,

Amanda


Sutton Strackes Burgundy Printed Dress

Style Stealers


Originally posted at: Sutton Stracke’s Burgundy Printed Dress

Read More
7 Considerations When Getting a Divorce Later in Life

divorce later in life

“Jennifer, my entire world has just crashed in front of me; David told me at breakfast this morning he is leaving us. He has fallen head over heels for a woman he met eight days ago. Yes, you heard that right; he met her eight days ago.”

Susan and David, in their 60s, had a tumultuous marriage that lasted for 40 years. They faced more than their share of challenges. Building a new business in a new country when they arrived in the US as newlyweds was one of them. While the business thrived, their marriage did not.
With almost half of marriages ending in divorce, here is a list of what you need to do should you decide to separate.

Take Stock of Your Finances

What Do You Own?

First, make a list of property you own jointly or separately. Same with debts and expenses. Then consider how will you divide any property – the matrimonial home, the rental, the cottage?

List your financial institutions and account numbers for your bank accounts, credit cards, loans, and investments.

Make sure you have copies of financial information: statements for outstanding loans, recent pay stubs, and your tax returns for the past three years.

Waiving Joint Account Statements

When you co-sign for a loan, credit card, or line of credit, each of the joint borrowers has the right to receive the same information from the lender about the loan.

For example, if you cosigned for a credit card with your former partner, the lender must give each of you copies of the credit agreement and the monthly statements, unless you consented either verbally or in writing to waive this right.

Negating Waiver

If you have already waived your right to separate disclosure, you can change your consent if you decide you would like to receive information about the joint account or loan.

Making Informed Decisions

Know your rights and responsibilities related to joint accounts and loans so you can decide what to do with the joint assets or debts you share with your partner. Get advice from your lawyer on the best way to handle these.

Contact your financial institution for advice on how to protect your interests in your joint accounts, such as preventing further borrowing from a line of credit or withdrawals from a joint bank account.

Keep Relevant Documents and Get Acquainted with Specifics

While you are working out your separation or divorce, keep bills and receipts for expenses related to your family. This will be helpful later when you are working out how to divide your property.

If you don’t close your joint accounts and loans, both of you may continue to be legally entitled to the funds in any joint accounts, as well as responsible for repaying any debts, even if your separation agreement states that only one person is responsible.

If one borrower doesn’t pay the debt, the lender can demand that any borrower listed in the loan or credit agreement pay the entire amount or continue making regular payments.

For certain credit cards, authorized users (also called “secondary cardholders”) can be held responsible for any outstanding balances, even if they did not sign the credit card application. To find out whether you are responsible, read your credit agreement or ask your lender.

Once you have closed joint accounts or paid off joint loans, check your credit report to make sure your financial information has been updated.

Establish Your Own Accounts and Deal with Joint Accounts

Make Your Accounts Your Own

Open your own checking and savings accounts and establish your own credit if you haven’t done so already.

Then go ahead and update your direct deposit information for paychecks, government checks, and any other regular payments you receive to ensure they are deposited to your own account.

Credit History

Make sure you have a credit history or start one. It’s important to have a credit history if you want to apply for credit or loans, such as credit cards or a mortgage. Some landlords and employers will check your credit history before considering you for an apartment or a job.

This can be an issue if most or all of a couple’s accounts and bills were registered and paid under one spouse’s name. As a result, the other spouse may have a low credit score. Take steps to build your credit history so that you have more financial options.

How Will You Split Your Pensions? And What About Extended Health Care Benefits?

This is of greater concern if one partner makes a substantially lesser income or may have taken time off work to raise the children.

Health care benefits are not equal from one company to the next. This is of greater concern if only one partner worked.

What Else to Consider

  • Take your time before jumping in with someone new!
  • Get emotional support from a family counsellor or a minister at your church.
  • Practice self-care.
  • Do not pit your adult children against your spouse. They will always be a part of him/her. No matter how old your adult children are, they will experience a sense of loss if your marriage were to end. They do not need to face an additional loss of a relationship with a parent as a result of the separation.

Divorce is both financially and emotionally stressful. Anyone thinking of separating should seek legal advice as soon as they can. The laws that apply to financial matters such as property division and spousal support depend on where you live.

If you and your former partner need assistance in reaching an agreement on these issues, you can consult several resources:

  • lawyers and notaries – who specialize in family law
  • mediators
  • arbitrators
  • financial advisors
  • credit counselors.

Let’s Have a Conversation:

Have you been considering a divorce? Do you think you will experience difficulties splitting joint property, accounts, etc.? How can you help yourself in the financial department before making the final decision to divorce? Do you have any specific questions about divorce financial planning? Please share them in the comments below.

Read More